
Cashew—Expense Budget Tracker
- Rating
- 4.7
- Downloads
- 500.00K
- Content Rating
- Everyone
Cashew—Expense Budget Tracker - Screenshots
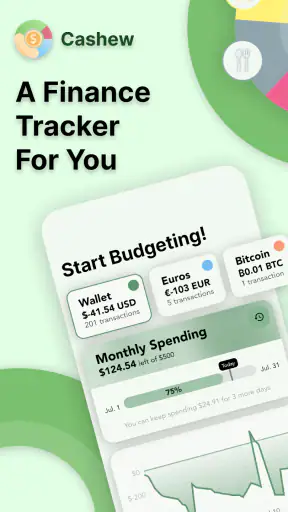
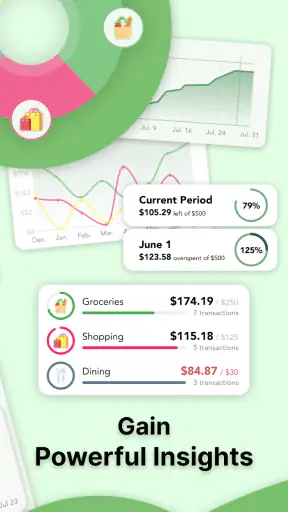
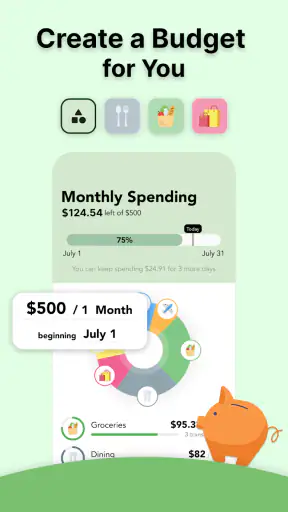
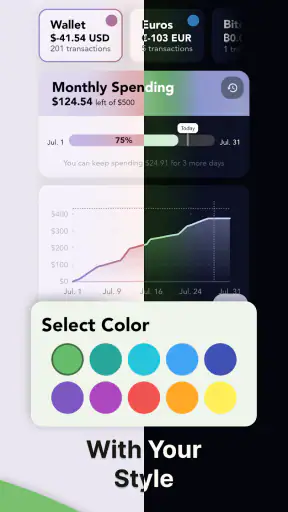
Pros
- Clean interface makes daily expense tracking quick and easy.
- Flexible categories help organize spending across different needs.
- Recurring transactions reduce the effort of logging regular bills.
- Budget alerts can help prevent overspending before it becomes a problem.
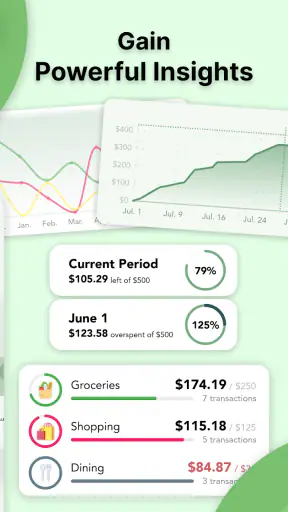
- Useful charts make spending patterns easier to understand at a glance.
Cons
- Some advanced budgeting tools may require a paid subscription.
- Manual entry can become time-consuming for users with many transactions.
- Limited bank integration may require entering expenses by hand.
- The app may feel overwhelming until categories and budgets are configured.
- Syncing data across devices may depend on account or cloud settings.
Cashew—Expense Budget Tracker - Description
- App Name
- Cashew—Expense Budget Tracker
- Package Name
- com.budget.tracker_app
- Developer
- Dapper App Developer
- Category
- Finance
- Last Updated
- Aug 21, 2023
- Version
- 6.6.11
Managing money on a phone sounds simple until the small purchases start disappearing into the background. A coffee here, a delivery charge there, and suddenly the monthly total feels disconnected from what I remember spending. Cashew—Expense Budget Tracker is built for that exact problem: it is a finance app that puts expense recording and budgeting into a more focused mobile routine. After using it, I found its strongest quality was not flashy financial analysis, but the way it encourages a quick check-in before everyday spending becomes difficult to understand.
The app is free to download, with optional in-app purchases ranging from $1.49 to $19.99 per item. It is suitable for Everyone, runs on Android 7.0 or later, and is developed by Dapper App Developer. Its current version is 6.6.11, and the app has built a 4.7 average from around 27 thousand ratings, alongside over 500 thousand installs. Those figures suggest that Cashew has found an audience among people who want a dedicated expense tracker rather than a full banking replacement.
How Cashew feels when your connection is part of the routine
The most important thing to understand is that Cashew is a hands-on tracking tool, not something I would treat as a complete substitute for a bank application. The useful habit is opening it when a purchase happens, recording the amount, and giving that expense enough context to be useful later. That workflow makes the phone central to the experience, so network conditions can affect how comfortable the process feels even when the financial decision itself is happening away from home.
At a checkout counter, on public transport, or while walking between appointments, I want an expense tracker to demand as little attention as possible. Cashew fits that kind of moment better than a spreadsheet because the purpose is already narrowed down to personal spending. I do not need to build formulas or maintain a separate document. The trade-off is that a focused tracker depends more on my consistency: if I postpone entries, the app cannot reconstruct the missing context from memory.
I would be careful about assuming that every part of the experience behaves identically without a connection. The available product information does not establish an offline workflow, so I would not choose Cashew on the promise that it can always replace a notebook in a dead zone. My practical advice is to try the recording flow in the places where you normally shop and commute, then decide whether it remains dependable enough for your routine. That small test matters more than a general claim about mobile convenience.
Why the quick-entry habit matters more than elaborate planning
Many people begin budgeting with ambitious categories and detailed targets, then stop using the system because every entry feels like administration. Cashew makes more sense when I treat it as a short daily checkpoint. I record the purchase while I still know what it was for, rather than waiting until the end of the week and trying to decode a bank statement full of vague merchant names.
A useful approach is to create a simple distinction between expenses that repeat and expenses that drift. Rent, subscriptions, and regular bills are easy to anticipate. Snacks, transport changes, impulse purchases, and small household items are where memory usually fails. I would use the tracker primarily to expose that second group. The result is more actionable than simply seeing a large monthly total, because it shows which flexible habits are pushing the budget off course.
There is also a psychological advantage to entering a small purchase immediately. The act is not a punishment and does not require waiting for a monthly review. It gives the expense a place in the plan while the decision is still fresh. For someone who dislikes traditional budgeting, that lighter rhythm may be the difference between maintaining a record and abandoning it.
Using it in real mobile situations
Imagine I am working away from home and buy lunch, pay for a short journey, and pick up a few items from a convenience shop. None of those transactions is individually dramatic, but together they can quietly replace the meal plan I intended to follow. With Cashew, I would record each one as it happens or during the next calm pause, then look at the combined pattern rather than judging one purchase in isolation.
The best moment for review is not necessarily late at night. I prefer checking spending before another decision, such as ordering dinner or making an unplanned online purchase. That turns the app from a passive archive into a prompt for action. If the food category is already higher than expected, I can change the next choice while the month still has room to recover.
For couples or households, the app may be useful as a personal spending log, but I would not assume that it automatically replaces a shared financial system. A household budget often needs agreed ownership, synchronized records, and clear rules for reimbursements. If those are essential to you, compare the time required to enter and reconcile everything with the convenience of a dedicated shared tool. Cashew is most naturally suited to an individual who wants clearer control over personal outgoings.
What happens when the routine breaks
Every tracker faces the same difficult moment: I forget to enter something, lose track of a receipt, or open the app after several busy days. The recovery strategy I recommend is not to recreate every detail with false confidence. Start with the transactions you can identify, mark the uncertain ones in a temporary mental group, and use the next review to improve the habit rather than trying to achieve a perfect historical record.
This is where a mobile tracker can expose both its strength and its weakness. The strength is immediacy: the phone is usually nearby when spending happens. The weakness is that the phone can also be distracting, unavailable, low on battery, or operating in a place with unreliable service. If your budget depends on perfect real-time entry, that fragility can become frustrating. I would keep a brief fallback note for unusual situations and transfer it into Cashew when I can give the entries proper attention.
Another practical recovery technique is to review by spending occasion instead of by isolated transaction. If I remember a supermarket visit but not every item, I can reconstruct the total from the receipt or payment record and then assign it sensibly. That is faster than searching my memory for each small purchase. The tracker becomes more useful when the information is accurate enough to guide decisions, not when the process turns into an accounting exercise.
Connectivity adds another layer to failure recovery. If a screen takes longer to load or a network-dependent action cannot complete, I would avoid repeatedly tapping and accidentally creating uncertainty about whether an entry was saved. Pause, check the visible result, and confirm the record before trying again. This is basic mobile discipline, but it matters more in a finance app because duplicate entries can distort the very budget I am trying to understand.
Being deliberate with data and network use
Expense tracking is personal by nature, so I prefer using Cashew with a clear idea of what information I am entering and when I am comfortable doing it. I do not need to write a detailed description for every purchase. A concise label that will still make sense during a monthly review is often better than a long note typed while standing in a queue. This also reduces the time spent on the phone and makes the habit easier to sustain.
When I am travelling or using a limited mobile connection, I would avoid treating the app as a place to experiment with complicated changes during a rushed purchase. I would prepare the budget structure when I have a stable connection and a few uninterrupted minutes, then keep transaction entries concise while moving around. Because the product information does not establish exactly which tasks work without connectivity, I would test the specific actions I rely on instead of assuming that every screen is available everywhere.
That cautious approach is not a criticism unique to Cashew. It is a sensible standard for any finance app used on the move. A tracker should fit into real life, where connections vary and attention is divided, but the user still has responsibility for checking that records are complete. If the app is part of your financial routine, a periodic review against your bank statement or receipts remains worthwhile. The tracker helps organize your understanding; it should not be the only place you verify important amounts.
There is a useful trade-off between detail and speed. More categories can reveal more patterns, but too many categories make entry tiresome and encourage skipped transactions. I would begin with broad groups such as food, transport, recurring bills, household purchases, and discretionary spending. Only split a group when the distinction changes what I will do next month. That keeps the system personal instead of turning it into a complicated classification project.
Where it stands against familiar alternatives
The obvious alternative is a spreadsheet. A spreadsheet offers flexibility and can be shaped around unusual household arrangements, but it usually requires more manual maintenance and is less comfortable for quick entries on a phone. Cashew is the better fit when I want a purpose-built place to record spending without designing the structure myself. The spreadsheet wins when I need custom calculations, extensive reporting, or a workflow shared across several people.
A bank app is another common substitute. Bank apps are excellent for checking actual transactions and balances, but they may not encourage the same forward-looking behavior as a dedicated budget tracker. Cashew is useful before the statement becomes a retrospective report: I can decide what an expense means in my own plan and notice a pattern while there is still time to adjust. On the other hand, a bank app remains the authority for confirming what was actually charged, especially when pending payments or refunds are involved.
Some people use a notes app or a paper wallet notebook. Those options can be wonderfully reliable for quick capture because they have almost no learning curve. Their weakness is the later review: totals and patterns require extra work. Cashew earns its place when I want the entries to become an ongoing picture of spending rather than a pile of reminders. If I only record a few cash purchases occasionally, paper may genuinely be simpler.
The free entry point makes it reasonable to test the workflow before paying for anything. Still, I would look carefully at which optional purchase, if any, improves my own routine rather than assuming that every paid addition is necessary. A budget app should save attention, not create pressure to unlock a system I have not yet learned to use.
Who will benefit, and who should look elsewhere
I would recommend Cashew to someone who wants a dedicated personal expense tracker, prefers recording purchases from a phone, and is willing to build a small daily habit. It is especially suitable for people whose main problem is not a lack of financial information, but a lack of visibility into flexible spending. Students, first-time budgeters, and anyone trying to reduce unplanned food or shopping costs can get value from that focused approach.
I would be less enthusiastic for a user who expects automatic banking integration, a complete investment dashboard, or a sophisticated household accounting system. Those needs call for a broader financial platform. I would also hesitate if you know you will never enter purchases manually. No expense tracker can be effective when the central behavior does not happen, and Cashew’s focused design does not remove that responsibility.
Someone with an irregular income can still use it, but the budgeting method needs more care. Instead of treating every month as identical, I would set conservative expectations and review spending more frequently. A fixed plan can be misleading when earnings change, so the app is better used as a visibility tool than as a promise that a particular limit will always fit.
My connectivity verdict
Cashew works best when I see it as a lightweight financial checkpoint that travels with me. Network conditions matter because mobile actions do not always happen in ideal places, yet the more important question is whether I can maintain a dependable recording habit and verify the result when necessary. I would test it in my normal shopping and commuting environments, keep entries concise, and avoid assuming offline behavior that has not been established.
After that adjustment, the app has a clear purpose. It is not trying to be my bank, my spreadsheet, and my entire financial life at once. It gives personal spending a dedicated home and makes everyday decisions easier to review later. The free starting point lowers the risk of trying it, while the optional purchases mean I can judge the basic routine before spending more.
My final view is positive, with one important condition: Cashew rewards consistency more than curiosity. If I enter expenses promptly and use reviews to change real choices, it can turn vague money worries into specific patterns I can act on. If I want automatic records, shared household controls, or deep financial analysis, I would choose a different category of tool. For a personal, mobile-first expense habit, though, Cashew—Expense Budget Tracker is a practical option that keeps its attention on the part of budgeting most people struggle to maintain.
FAQ
What is Cashew—Expense Budget Tracker used for?
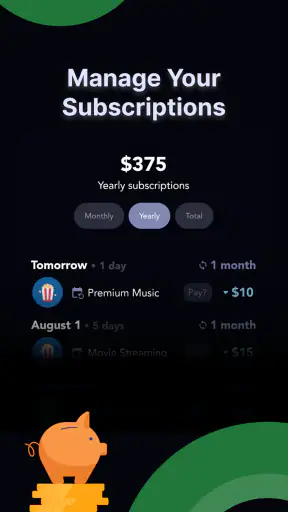
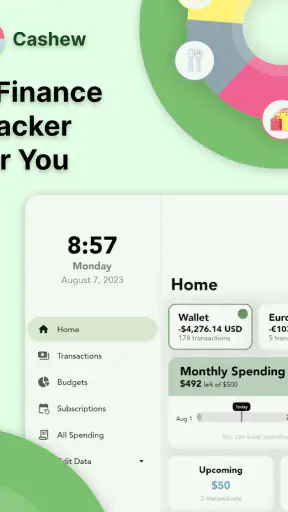
Cashew is a personal finance app designed to help you record expenses, organize income, monitor spending habits, and manage budgets in one place. After setting up your accounts and categories, you can review where your money goes and compare your spending with your limits. It is useful for everyday budgeting, household finances, subscriptions, savings goals, and general financial planning.
Can I use Cashew to track multiple accounts, currencies, or shared finances?
Cashew is built for users who want to keep more than one part of their financial life organized. Depending on the version and platform features available, you may be able to create separate accounts, add different currencies, and manage transactions across cash, bank, card, or other sources. Users should check the current app listing because supported options and advanced features may vary by device, region, or subscription plan.
Does Cashew automatically connect to my bank account?
Cashew primarily focuses on personal expense tracking and budgeting, so you should not assume that every bank will connect automatically. In many cases, transactions can be entered manually or imported through supported methods. This approach gives you more control over your financial data, but it may require regular updates. Before downloading, review the current permissions and integration details to confirm whether your bank is supported.
Is my financial information safe when using Cashew?
Because a budgeting app can contain sensitive information, privacy and security should be considered before adding real account details. Cashew may offer device-based protection, backups, or synchronization features, but the exact safeguards depend on the current release and your settings. Avoid sharing passwords or banking credentials, use a strong device lock, review requested permissions, and read the app’s privacy policy before enabling cloud-related features.
Is Cashew free, and are there any limitations or in-app purchases?
Cashew may provide a free way to begin tracking expenses, while certain advanced tools, customization options, synchronization features, or premium services can depend on the plan offered in your region. Pricing and included features may change over time, so check the Google Play Store or Apple App Store listing before downloading. Also review trial terms and recurring subscription details if a premium upgrade is offered.


